A company can achieve impressive revenue growth, attract major investors, and establish a strong market position without being prepared to operate as a public business. Going public introduces financial reporting obligations, governance expectations, regulatory scrutiny, and investor demands that differ considerably from those of private ownership. The gap between commercial success and public-company readiness can create expensive problems if leadership waits until an initial public offering (IPO) is approaching to address them.
Financial Reporting Must Become More Disciplined
Private companies often develop financial reporting practices around the needs of founders, lenders, and existing investors. Public companies face stricter reporting requirements and deadlines. Finance teams must be capable of producing accurate financial statements, maintaining supporting documentation, and responding to audit requests within established reporting schedules.
A company that relies on spreadsheets, manual reconciliations, and a few experienced employees may struggle as reporting demands increase. Leadership should evaluate accounting systems, financial close procedures, internal controls, and staff capacity well before pursuing an IPO.
Internal Controls Need Formal Structure
Rapidly growing businesses sometimes depend on informal approvals and relationships between long-serving employees. Those arrangements become harder to defend when financial reporting faces greater scrutiny. Public-company preparation requires examining how transactions are authorized, recorded, reviewed, and corrected.
Responsibilities should be clearly separated where appropriate. For example, the employee approving a payment should not automatically control every stage of its processing and reconciliation. Companies should document important procedures, establish review controls, and test whether those controls operate consistently.
Governance Must Evolve Beyond the Founders
Private businesses may have boards dominated by founders, early investors, or executives with close personal relationships. Public ownership introduces additional governance considerations, including board independence, committee responsibilities, executive compensation oversight, and communication with shareholders.
Leadership should evaluate whether directors have the experience needed to oversee financial reporting, risk management, strategy, and executive performance. Clear governance structures can also reduce confusion about which decisions belong to management and which require board involvement.
Technology Must Support Greater Scrutiny
A business preparing for public ownership needs reliable information across finance, operations, legal, and compliance functions. Disconnected systems can create inconsistent records, duplicated work, and delays when teams need information for audits or disclosures.
Companies that have expanded through acquisitions may face additional challenges integrating financial and operational data. Tools such as M&A software can support transaction management and integration activities, but leadership must still establish consistent reporting standards across the combined organization. Technology investments should address specific operational weaknesses rather than simply adding new platforms.
Investor Communication Becomes a Continuing Responsibility
Private companies generally communicate with a relatively small group of owners. Public companies must provide information to a broader investor audience while following applicable disclosure requirements. Executives need processes for preparing financial announcements, discussing business performance, and managing material information.
Forecasting discipline becomes especially important. Leadership should be able to explain financial results, significant risks, and changes in business performance without relying on unsupported projections. Investor relations responsibilities should be established before the company enters public markets.
Start Readiness Reviews Before the Offering
IPO preparation should begin with a realistic assessment of current capabilities. Companies can examine financial reporting, governance, internal controls, technology, staffing, and regulatory requirements to identify gaps. Each weakness should have an assigned owner, corrective action, and target completion date. Some improvements may require several reporting cycles to demonstrate consistent performance.
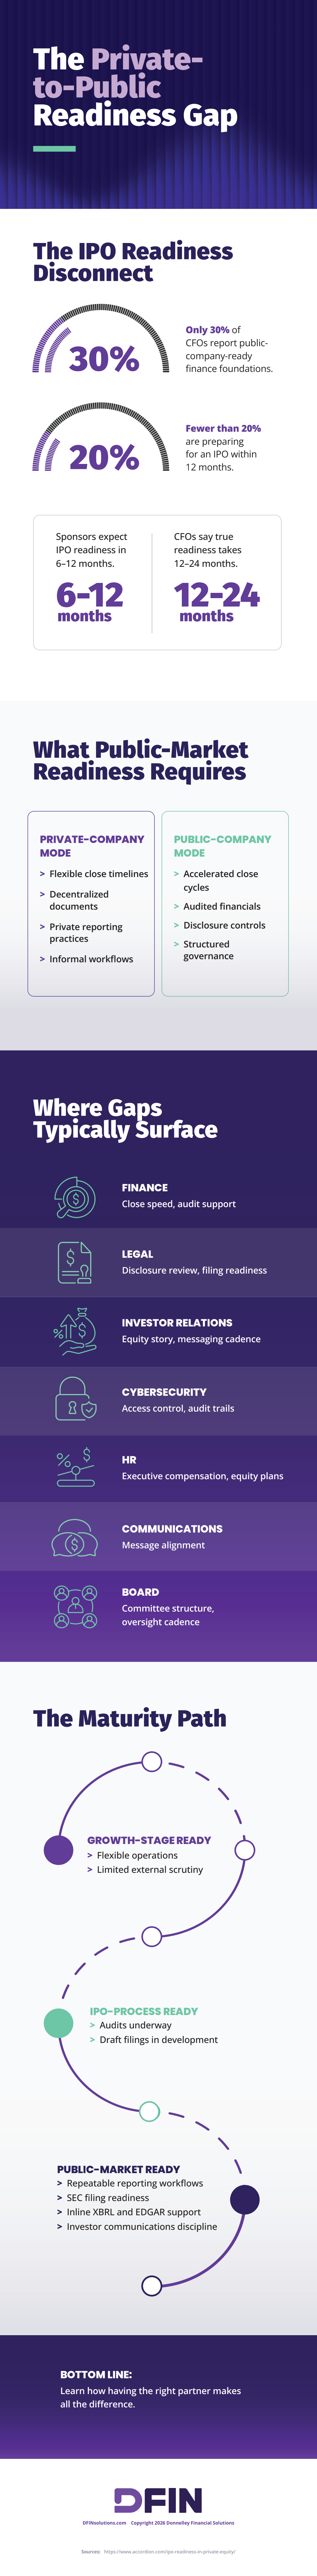
The private-to-public readiness gap is ultimately an operational challenge. Revenue growth and investor interest may create an opportunity to pursue an IPO, but they do not guarantee that a company can meet the responsibilities of public ownership. To learn more, feel free to look over the accompanying infographic below.